Protecting Your Wealth in a Bubble Environment — Practical Steps Every Investor Should Take
A practical guide to the concrete steps investors have historically taken to protect wealth during bubble periods — from portfolio diversification and gold allocation to document protection and liquidity management.
By Twin · @TwinTowerCity·
Key Takeaways
- →Successful bubble-era wealth protection requires maintaining 20-30% cash positions during peak euphoria periods despite opportunity costs.
- →Historical bubble protection strategies center on portfolio diversification, gold allocation, and maintaining higher liquidity than conventional wisdom suggests.
- →Protective investment actions during bubble peaks typically underperform markets by 15-40% annually until the eventual collapse occurs.
- →Warren Buffett accumulated $44 billion cash before 2008 while John Paulson shorted mortgage securities starting in 2006.
- →Wealth preservation during bubbles demands acting against prevailing sentiment when protective strategies appear financially irrational to peers.
Peak Year
Not established
Crash Year
Ongoing
Location
Global
Asset Class
Multi-Asset
Severity
Recognising the characteristics of a financial bubble is a vital first step for any prudent investor. However, identification alone is insufficient. Historical analysis shows that many market participants correctly identify speculative excess but fail to take meaningful protective action, often due to a fear of missing out on further gains or an underestimation of the severity of the eventual collapse. True financial prudence lies in translating this awareness into a concrete, pre-planned strategy designed to preserve capital when the speculative tide inevitably turns.
This guide outlines six practical categories of action every investor should consider when operating in what they perceive to be a bubble environment. These steps are not about timing the market peak, an impossible feat, but about building a robust financial framework that can withstand systemic shocks. We will cover portfolio diversification, holding physical gold, securing essential documents, managing liquidity, diversifying internationally, and, crucially, preparing for the psychological challenges of acting against a euphoric crowd.
Portfolio Diversification
The first principle of risk management in a bubble is to reduce concentrated exposure to the inflating asset class. If you suspect equities are in a bubble, it is logical to reduce your allocation to equities. This means systematically rebalancing your portfolio, trimming positions in overvalued assets and reallocating the proceeds to non-correlated or negatively-correlated safe havens. This disciplined approach runs counter to the euphoric sentiment of a bull market but is essential for capital preservation.
An asset is non-correlated if its price moves independently of the bubble asset, while a negatively-correlated asset tends to rise when the bubble asset falls. Historically, physical gold has demonstrated its value as a safe-haven asset during equity market downturns. For instance:
- During the 2008 Global Financial Crisis, as global stock markets plunged, gold prices rose by +5.5% in US dollar terms.
- In the 2000–2002 bear market following the dot-com bust, gold gained approximately +15%.
- During the sharp COVID-19 market drawdown in early 2020, gold rallied by nearly +25%.
This historical performance underscores gold's role as a portfolio insurance mechanism. Other potential diversifiers include cash, high-quality government bonds, and certain alternative assets. However, in an environment of widespread speculative excess, often dubbed the Everything Bubble, even traditional safe havens like bonds can become sources of risk. The lesson from major crashes like the 1929 event is that diversification away from the epicentre of the speculation is paramount for survival.
Physical Gold Allocation
While many investors gain exposure to gold through financial instruments like Exchange-Traded Funds (ETFs), it is critical to understand the distinction between these 'paper' assets and outright ownership of allocated physical gold. Gold ETFs are convenient, but they introduce layers of counterparty risk that can become acute during a systemic financial crisis—the very time you need your safe-haven asset to perform flawlessly.
An ETF share represents a claim on gold held by a custodian, managed by the ETF provider. The value chain involves authorised participants (large banks) who create and redeem ETF shares. In a major crisis, any of these entities could fail, potentially freezing redemptions or creating a significant disconnect between the ETF's price and the underlying spot price of gold. Furthermore, much of the gold held by institutions is unallocated, meaning it exists as a creditor entry on a bank's balance sheet and is often leased or rehypothecated. If that institution fails, investors are left as unsecured creditors.
Allocated physical gold ownership eliminates these risks. In an allocated storage model, specific, segregated bars or coins are held in a professional vault in your name. You are the outright owner, and the gold is not on the storage provider's balance sheet. This ensures that your asset is secure even if the storage company itself faces financial distress. Providers like BullionVault offer allocated storage across multiple international jurisdictions, such as Zurich, London, and Singapore, which adds a layer of geographic diversification to your physical holdings.
Document and Asset Protection
Wealth protection extends beyond financial assets. In a severe crisis, which may involve banking system outages, cyberattacks, or even natural disasters, access to critical legal and personal documents can be as important as access to liquidity. We live in an increasingly digital world, but relying solely on cloud storage or institutional records for proof of ownership can be a critical vulnerability.
You should maintain physical, hard copies of all essential documents in a secure, accessible location. This provides a definitive fallback if digital systems fail or you are unable to access them. Key documents to secure include:
- Proof of Ownership: Property titles, vehicle registrations, and physical share or bond certificates if you have them.
- Financial Records: Wills, trust documents, and records of beneficiaries for all accounts.
- Insurance Policies: Life, health, home, and disability insurance contracts.
- Personal Identification: Passports, birth certificates, and marriage certificates.
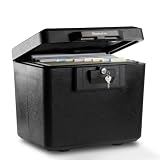
A simple and effective solution for protecting these items is a durable fireproof and waterproof document safe kept within your home. For example, a product like the SentrySafe Fireproof Document Box can protect papers and digital media from fire and water damage, ensuring your most important records survive a physical emergency.
Liquidity Management
In a financial crisis, cash is not just king; it is the entire kingdom. When markets seize up, the ability to meet expenses without being forced to sell assets at fire-sale prices is a crucial survival tool. A core tenet of defensive financial planning is to maintain a significant liquidity buffer before a crisis hits. A common guideline is to hold 6 to 12 months' worth of essential living expenses in cash or true cash equivalents (e.g., short-term government treasury bills).
The danger of illiquidity was starkly demonstrated during the 2008 liquidity crisis. As panic spread, markets for assets previously considered highly liquid and safe, such as AAA-rated mortgage-backed securities, completely froze. There were simply no buyers at any reasonable price. Investors who needed to raise cash were forced to sell their most liquid and high-quality assets (like blue-chip stocks) instead, causing a contagion effect that spread the crisis throughout the financial system. Holding a cash reserve outside the market system provides a firewall, allowing you to ride out the storm without becoming a forced seller at the worst possible moment.
International Diversification
True asset diversification includes a geographic component. Concentrating all your assets within a single political and economic jurisdiction exposes you to sovereign risk. If a bubble's collapse triggers a severe economic downturn in your home country, the government may resort to desperate measures to maintain control, including capital controls, punitive taxation, or even asset confiscation.
International diversification is more than simply owning foreign stocks through a local broker. It involves holding assets in different legal jurisdictions. This could mean owning physical gold in a Swiss vault, holding foreign currency in an offshore bank account, or owning real estate in another country. The goal is to place a portion of your wealth beyond the immediate reach of a single government. This strategy is particularly relevant for investors concerned about the sustainability of the global bond bubble, the unwinding of which could trigger sovereign debt crises in multiple developed nations and lead to a rise in financial protectionism and capital restrictions.
Psychological Preparation
Perhaps the most difficult step is preparing yourself mentally to act against the overwhelming social and emotional currents of a market mania. The field of behavioural finance has shown that human beings are not the rational actors of classical economic theory. During a bubble, powerful psychological biases conspire to keep investors fully invested, or even encourage them to increase their risk exposure, right up to the peak.
Key biases to recognise include:
- Fear of Missing Out (FOMO): Watching neighbours and colleagues make seemingly effortless profits creates intense pressure to participate, overriding rational risk assessment.
- Social Proof: When everyone around us is doing the same thing (buying inflating assets), we assume it must be the correct thing to do. This "safety in numbers" feeling is a dangerous illusion in financial markets.
- Loss Aversion in Reverse: The pain of a loss is felt more strongly than the pleasure of an equivalent gain. In a bubble, this is inverted: the anticipated regret of missing out on future gains becomes more powerful than the fear of a potential loss.
From the Dutch tulip mania of the 17th century to the meme stock bubble of the 21st, the psychological dynamics are identical. The only defence is to have a pre-defined, rules-based plan for de-risking and to follow it with discipline, even when every emotional impulse tells you to stay in the game.
Translating Awareness into Action
The lessons of history are clear: financial bubbles are a recurring feature of market economies, and their collapse can be devastating to unprepared investors. The practical steps outlined above provide a framework for building resilience, not for timing the market. Warnings and analysis are only valuable if they are translated into disciplined, proactive measures. The ongoing data provided by the Bubblepedia heatmap and our live indicators can help you assess the current environment and maintain your protective financial framework over time.
Recommended
Key Statistics
Gold in 2008 GFC
Gold rose 5.5% while global equities fell over 40%
Gold in Dot-Com Crash
Gold rose approximately 15% during the 2000-2002 equity bear market
Liquidity Premium
In 2008, even AAA-rated assets became unsellable within weeks
Document Loss
FEMA estimates 25% of businesses fail within a year after a major disaster due to document loss
Correlation Breakdown
In 2022 both equities and bonds fell simultaneously — traditional 60/40 diversification failed
Cash Buffer
Financial advisers recommend 6-12 months expenses in liquid form before investing in illiquid assets
Warning Signs
- When bubble conditions are identified, the protective steps are: reduce concentration in the inflating asset, increase gold allocation, ensure document security, maintain liquidity, and review international diversification.
Lessons Learned
The investors who best preserved wealth through historical crises acted early and unconventionally. Warren Buffett raised cash before 2008. John Paulson shorted mortgage securities in 2006. Protective action during euphoria feels wrong and often underperforms until the crash.
Frequently Asked Questions
What are the main warning signs that indicate a financial bubble is forming?
Key bubble warning signs include rapidly rising asset prices disconnected from fundamentals, widespread speculation by inexperienced investors, easy credit conditions, media euphoria, and the belief that 'this time is different.' Additional indicators are extreme valuations, margin buying increases, and when conversations at social gatherings focus heavily on investment gains in specific sectors.
How much of a portfolio should be allocated to gold during bubble periods?
Financial advisors historically recommend 5-10% gold allocation during normal times, increasing to 10-20% during bubble periods for wealth preservation. Gold has served as a hedge during major bubble collapses, including the 2000 dot-com crash and 2008 financial crisis, though it doesn't guarantee protection against all market downturns.
What caused investors to lose wealth during historical financial bubbles?
Investors lost wealth during bubbles primarily due to overleveraging, lack of diversification, panic selling at market bottoms, and failing to maintain adequate cash reserves. Many concentrated holdings in bubble assets, used borrowed money to invest, and abandoned risk management principles during euphoric market phases, amplifying losses when bubbles burst.
What key lesson do financial bubbles teach about wealth protection strategies?
Bubbles teach that maintaining liquidity, diversification, and emotional discipline are crucial for wealth preservation. The most important lesson is that no asset class is immune to extreme overvaluation, and investors who survive bubbles best typically maintain 10-20% cash reserves, avoid excessive leverage, and stick to predetermined exit strategies regardless of market euphoria.
Current Relevance
With CAPE at 35, gold at elevated levels, and crypto recovering, the conditions present in late 2024 and 2025 echo multiple historical bubble periods simultaneously. The diversification steps outlined here are relevant to any investor with significant equity or crypto exposure.
Explore gold storage options
Gold is not a guaranteed hedge against crashes. Prices can fall; storage fees and custody risks also matter.
Affiliate link: Bubblepedia may earn a commission. Not a recommendation; investment values can fall.
Get Bubblepedia in your inbox
Asset bubbles and market-history insights in your inbox.