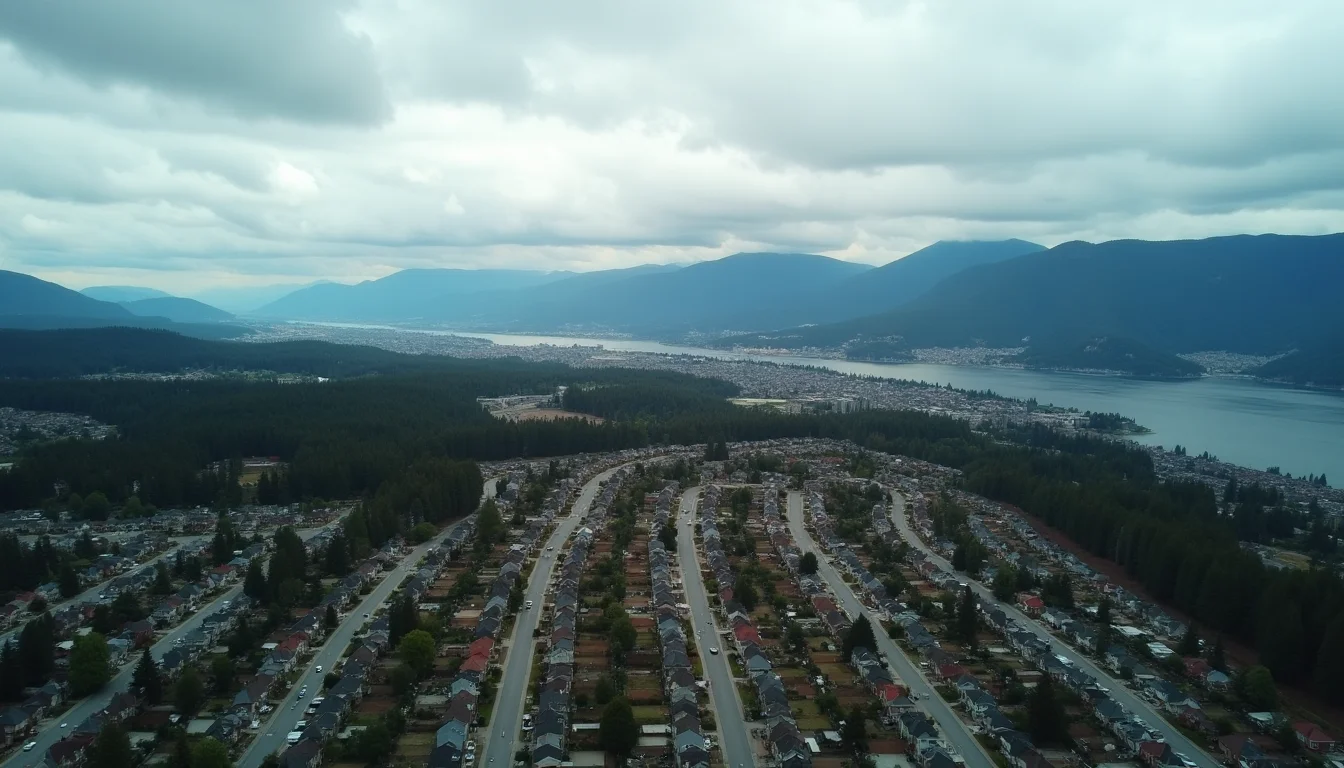
Canadian Property Bubble (2002-Present)
Canadian housing prices rose 375% nationally since 2002, with Toronto and Vancouver among the world's most expensive cities relative to income.
By Twin · @TwinTowerCity·
Key Takeaways
- →Canadian housing prices surged 375% nationally from 2002 to 2022, making Toronto and Vancouver globally unaffordable relative to incomes.
- →Immigration policy requiring sustained housing demand combined with loose monetary policy and restricted supply drove the prolonged price escalation.
- →The bubble peaked in 2022 when central bank interest rate increases finally began constraining mortgage affordability and buyer demand.
- →Housing wealth became the primary asset for Canada's voting majority, creating enormous paper wealth dependent on continued price appreciation.
- →Political reform becomes impossible when immigration policy, housing wealth, and voter interests align against supply increases or demand reduction.
Peak Year
2022
Crash Year
Ongoing
Location
Canada
Asset Class
Real Estate
Severity
What Caused the Canadian Property Bubble?
Canada's property bubble developed gradually over two decades, driven by a combination of factors that proved self-reinforcing. Record-high immigration — Canada admitted over 400,000 permanent residents annually by the early 2020s, plus hundreds of thousands of temporary workers and international students — created genuine demand pressure, particularly in Toronto and Vancouver. The Bank of Canada maintained historically low interest rates for most of the 2010s, with the overnight rate sitting at or below 1% for extended periods. Canadian mortgage rules, while stricter than pre-crisis US standards, still allowed high leverage: insured mortgages required only 5% down payments, with the Canada Mortgage and Housing Corporation (CMHC) providing government-backed mortgage insurance that transferred risk from lenders to taxpayers.
The Mania Phase
Canadian house prices roughly tripled between 2000 and 2022 in real terms. The acceleration during the COVID-19 pandemic was particularly dramatic: the national composite house price index rose approximately 50% between early 2020 and early 2022, as low interest rates, pandemic savings, work-from-home migration, and fear of missing out converged. In Toronto and Vancouver, detached homes regularly sold for hundreds of thousands above asking price, with buyers waiving inspection conditions and submitting offers within hours of listings appearing. 'Blind bidding' — where buyers could not see competing offers — amplified the frenzy. By 2022, the national average home price exceeded $800,000 CAD, with Toronto averaging over $1.3 million and Vancouver over $1.2 million. Household debt to disposable income reached approximately 185% — among the highest ratios in the developed world.
Peak Conditions
At the market's peak in early 2022, Canadian real estate had become arguably the most systemically important asset class in the national economy. Residential investment represented approximately 10% of GDP — roughly double the level in most peer economies. The total value of Canadian residential real estate exceeded $6 trillion CAD, dwarfing the combined market capitalisation of all publicly traded Canadian companies. The wealth effect from rising property values supported consumer spending, while construction employment reached record levels. The CMHC's mortgage insurance portfolio represented a contingent liability of hundreds of billions of dollars. Housing affordability reached its worst level since records began, with the price-to-income ratio in Toronto and Vancouver exceeding levels seen in London and New York.
How Did the Canadian Property Bubble Crash?
The Bank of Canada began raising interest rates aggressively in March 2022, eventually increasing the overnight rate from 0.25% to 5.0% by mid-2023. The impact on the housing market was immediate and significant. National average prices fell approximately 15-20% from the February 2022 peak by early 2023, with larger declines in suburban and exurban markets that had seen the most pandemic-era appreciation. Variable-rate mortgage holders — who comprised approximately 30% of outstanding mortgages — saw their payments increase by 40-60%. Fixed-rate borrowers faced 'payment shock' upon renewal, as mortgages originally taken at rates below 2% came up for renewal at rates above 5%. The 'mortgage renewal wall' — approximately $900 billion in mortgages scheduled for renewal between 2024 and 2026 — remained a source of significant anxiety.
Aftermath and Recovery
Unlike the US experience in 2008, Canada's property correction did not trigger widespread foreclosures or banking failures — partly because of stricter underwriting standards and partly because the government extended amortisation periods and offered other relief measures. However, the correction exposed structural problems in Canada's economic model. The country's productivity had stagnated for years as capital flowed into real estate rather than business investment. Immigration policy came under political scrutiny as the connection between population growth and housing unaffordability became a central public concern. The federal government reduced immigration targets and introduced restrictions on foreign buyers and temporary residents purchasing property.
Lasting Legacy
Canada's property bubble illustrates how democratic governments can become trapped by housing market dynamics. Rising prices benefit existing homeowners — who form a large and politically powerful constituency — while harming younger and lower-income Canadians who cannot enter the market. Every attempt to cool the market risks both economic recession and political backlash from homeowners who have built their financial futures around continued appreciation. The Canadian experience has become a cautionary tale about the dangers of allowing residential real estate to become the dominant store of national wealth, and about how immigration policy, monetary policy, and housing policy can interact to create outcomes that no single policy intended.
For Australian investors considering international property diversification in response to domestic bubble risk, Wise offers mid-market exchange rates for international property deposits and settlements — significantly cheaper than standard bank international wire fees.
The Structural Similarities and Differences with Australia
Canada and Australia entered the post-2008 period as the two major developed economies that did not experience a property crash during the global financial crisis. Both countries shared a roughly identical set of structural conditions: high immigration rates relative to housing supply growth, commodity-linked currencies that attracted foreign capital, banking systems concentrated in a handful of large institutions, and tax policies (most notably mortgage interest deductibility on investment properties in Canada and negative gearing in Australia) that subsidised property speculation. Both countries' property markets continued rising through 2008 and beyond while the United States, United Kingdom, Spain, and Ireland experienced devastating crashes.
The Canadian concentration is, however, even more extreme than Australia's. Where Australia's property capital is split between Sydney and Melbourne with significant secondary markets in Brisbane and Perth, Canada's property dynamics are dominated almost entirely by Toronto and Vancouver. The two cities together represent roughly 35% of Canada's population but capture over 60% of national real estate investment activity. Vancouver has consistently ranked as one of the world's least affordable property markets relative to local incomes, with median house prices reaching 13 times median household income at the 2022 peak.
The Foreign Buyer Premium
The role of foreign capital in Canadian property prices has been one of the most politically contentious questions in Canadian economic policy. Academic research, most notably by Joshua Gordon at Simon Fraser University, estimated that 10 to 15% of Vancouver and Toronto property purchases at the peak years of 2015 to 2017 were made by non-resident foreign buyers, primarily from mainland China. The political response began with British Columbia's introduction of a 15% foreign buyer tax in August 2016 (later raised to 20% in 2018) and Ontario's matching 15% non-resident speculation tax introduced in April 2017 (later raised to 25%).
The immediate effect of both taxes was a temporary price correction of 10 to 15% in the most exposed luxury segments, followed by a resumption of the broader upward trend driven by domestic demand and continued immigration. The federal government extended the response with a two-year ban on most foreign property purchases beginning January 2023, a measure that has since been extended through 2027. The political consensus that foreign buyers were a primary driver of unaffordability has not been fully supported by the data, which shows that the underlying drivers (low interest rates, supply constraints, and population growth) explain the majority of price appreciation.
The Mortgage Market Structure
The Canadian mortgage market has structural features that differentiate it sharply from both the American and Australian systems. Canadian mortgages are typically amortised over 25 to 30 years but renewed every 5 years at the prevailing market rate, creating what has become known as the renewal cliff. Borrowers who took 5-year fixed mortgages at 2% during 2020 and 2021 faced renewals at 5% or higher in 2025 and 2026, a payment shock that increases monthly mortgage costs by 35 to 50% on the same outstanding balance. Roughly $675 billion in Canadian mortgages renew between 2025 and 2026, the largest such cliff in Canadian history.
The Canadian system also requires mortgage insurance through the Canada Mortgage and Housing Corporation (CMHC) for any purchase with less than 20% down payment, creating a public sector backstop that absorbs losses on the most leveraged loans. Following the 2017 introduction of the B-20 mortgage stress test (which requires borrowers to qualify at the contract rate plus 2% or the Bank of Canada five-year benchmark, whichever is higher), new mortgage origination has been substantially more conservative than the loans that built the 2010 to 2022 boom. The system thus has a substantial cohort of pre-2017 borrowers facing the renewal cliff who would not qualify for their existing loans under current standards.
"The Canadian housing market is the most overvalued in the world relative to incomes and rents on virtually every metric." — Bloomberg Economics housing risk analysis, 2023
The Bank of Canada Rate Cycle
The Bank of Canada's tightening cycle from March 2022 to July 2023 raised the policy rate from 0.25% to 5.0%, the steepest tightening in modern Canadian history. The effect on the property market was immediate and severe: the national MLS Home Price Index fell 21% from its February 2022 peak to its January 2023 trough, the sharpest correction in Canadian property history. Toronto and Vancouver detached house prices fell 25 to 30% from peak in some neighbourhoods, with luxury segments (above $3 million) experiencing larger declines as the foreign buyer ban combined with rate increases to remove demand at the top of the market.
The recovery that began in late 2023 has been driven primarily by immigration policy. Canada admitted approximately 500,000 new permanent residents in 2023 and again in 2024, the highest absolute numbers in Canadian history and approximately 1.3% of the existing population annually. The mathematics of housing supply (Canada has built roughly 240,000 new homes annually against household formation of 350,000 to 400,000 driven by immigration) make sustained price declines structurally difficult absent either a recession or a sharp reduction in immigration intake. The federal government's October 2024 announcement reducing planned immigration to 395,000 in 2025 represents the first acknowledgement of this tension. The unresolved policy question, parallel to the issues facing the Australian property market, is whether housing affordability and current immigration levels can both be sustained.
Recommended Reading

Key Statistics
National Price Increase
375% since 2002
Vancouver Price/Income
~13:1
Toronto Price/Income
~10:1
Immigration
1M+ per year (2023)
Mortgage Renewal Shock
40-60% payment increase
Warning Signs
- Price-to-income ratios among highest globally
- Immigration targets set partly to sustain housing demand
- Massive mortgage renewal wave at higher rates ahead
- Foreign investment concentration in Vancouver and Toronto
Timeline
2002
Canadian property bull run begins in earnest
2010-15
Chinese investment drives Vancouver to extreme levels
2016-17
Foreign buyer taxes implemented in Vancouver and Toronto
2020
COVID stimulus accelerates price growth
2022
Bank of Canada raises rates aggressively
2023-24
Mortgage renewals at higher rates begin — financial stress rises
Lessons Learned
Canada demonstrates how immigration policy, central bank policy, and housing policy can become entangled in ways that make correction politically impossible. When housing wealth is the primary asset of the voting majority, and immigration is required to sustain demand, the incentive structure makes meaningful reform — increased supply, reduced demand-side stimulus, or higher rates — politically toxic.
Frequently Asked Questions
What caused the Canadian housing bubble?
The Canadian property bubble was driven by historically low interest rates maintained by the Bank of Canada, increased immigration and foreign investment (particularly from China), speculative investing, and relaxed lending standards. Government policies like the First-Time Home Buyer Incentive and tax advantages for real estate investment also contributed to inflated demand and prices.
How much have Canadian house prices increased since 2002?
Canadian housing prices have risen approximately 375% nationally since 2002. Toronto and Vancouver experienced even steeper increases, with average home prices exceeding $1 million by 2021. This represents one of the largest sustained property price increases among developed nations, far outpacing income growth and inflation rates.
What were the warning signs of Canada's housing bubble?
Key warning signs included house prices rising far faster than incomes, with price-to-income ratios reaching dangerous levels in major cities. Other indicators were speculative buying, bidding wars becoming commonplace, extremely low rental yields, household debt reaching record highs, and properties selling significantly above asking prices within days of listing.
What lessons does the Canadian housing bubble teach investors?
The Canadian bubble demonstrates how prolonged low interest rates can create unsustainable asset inflation. It shows the importance of monitoring price-to-income ratios and household debt levels as early warning indicators. Investors learned that government intervention and foreign capital flows can significantly distort local markets beyond fundamental economic drivers.
Current Relevance
Canada faces its most significant housing affordability crisis in history, with an entire generation priced out of home ownership in major cities. The coming mortgage renewal wave at higher interest rates represents the most significant near-term risk to the Canadian economy.
Explore gold storage options
Gold is not a guaranteed hedge against crashes. Prices can fall; storage fees and custody risks also matter.
Affiliate link: Bubblepedia may earn a commission. Not a recommendation; investment values can fall.
Recommended Reading
Recent Analysis
Construction Productivity Crisis Prices New Housing Out of R
14 Nov 2026
German Commercial Property Risk: Bundesbank Warns of Decline
12 Nov 2026
India's $5.4 Trillion Stock Market Surge: Foreign Inflows Reclaim Fifth-Largest Position
12 Nov 2026
Australian Home Auctions Edge Higher After Fifth Rate Rise
9 Nov 2026
Australia Home Prices in 40-Year Bear Market
1 Nov 2026
Get Bubblepedia in your inbox
Asset bubbles and market-history insights in your inbox.