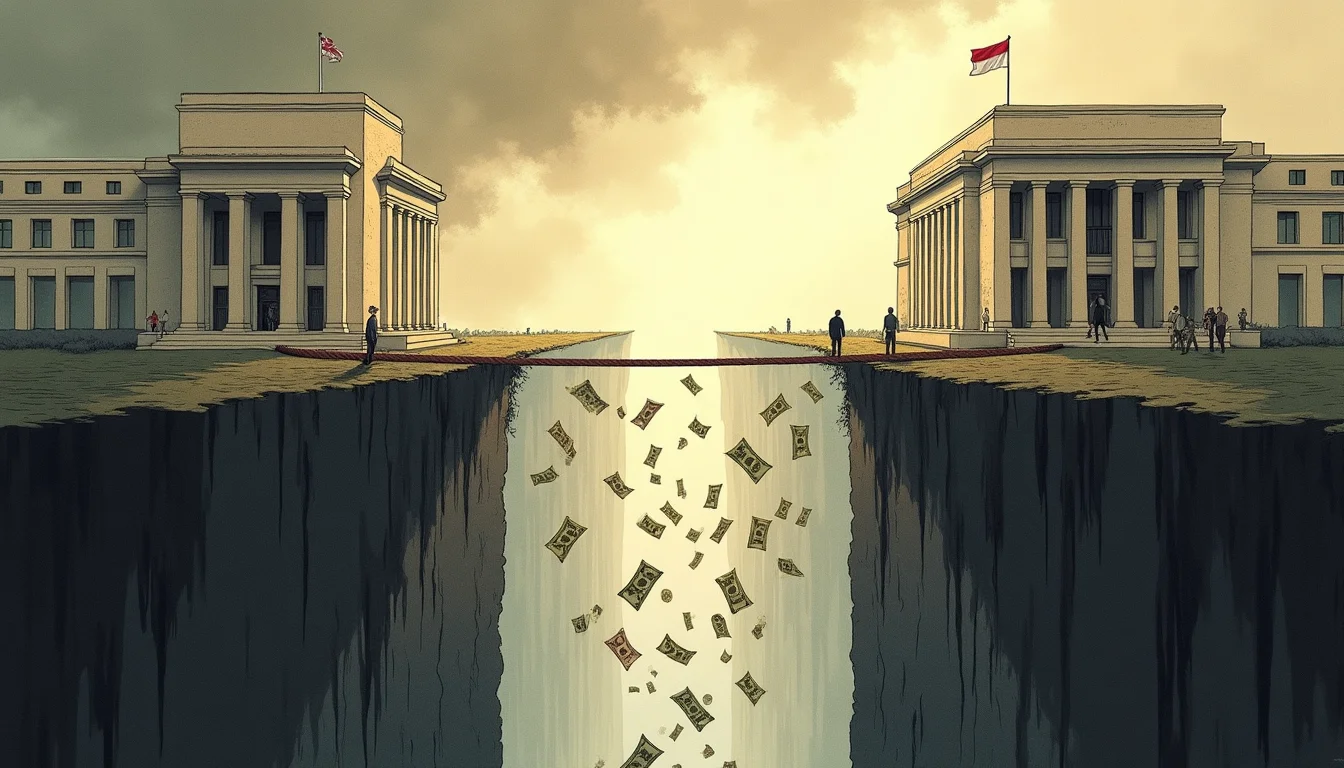
According to Bloomberg Markets, the departure of Bank Indonesia Governor Perry Warjiyo has placed the institution's policy credibility under fresh scrutiny at precisely the worst moment — just as bond traders are pricing a non-trivial probability of a Federal Reserve rate hike at this week's FOMC meeting. The confluence is not incidental. Central bank divergence — when major economies move monetary policy in opposite directions simultaneously — is one of the most reliable preconditions for the kind of speculative dislocation that Bubblepedia documents across centuries of financial history.
What Central Bank Divergence Actually Does to Capital
The mechanism is straightforward, even if its consequences are not. When the Fed tightens while emerging-market central banks face political pressure to hold or ease, the interest-rate differential widens. Capital — particularly the short-duration, yield-seeking variety that flooded into emerging markets during the 2020–2021 zero-rate era — reverses course. Currencies depreciate. Domestic bond yields spike to defend exchange rates. Equity markets reprice. The speed of that repricing depends almost entirely on how much of the prior inflow was speculative rather than structural.
Indonesia is a case study in this vulnerability. The rupiah has historically been among the more sensitive emerging-market currencies to Fed tightening cycles, given the country's reliance on portfolio inflows to fund its current account. A leadership transition at Bank Indonesia — regardless of the incoming governor's competence — introduces a period of policy ambiguity that markets punish swiftly. Analysts cited by Bloomberg have flagged that the timing raises questions about whether BI will prioritise currency defence or domestic growth, a dilemma that has no clean answer when the Fed is tightening.
Leveraged ETF mechanics compound the problem. These instruments rebalance daily, which means that on days of elevated volatility they mechanically amplify price moves in the underlying stocks. When that volatility is itself being driven by macro uncertainty — rate expectations, currency moves, central bank signalling — the feedback loop between derivatives positioning and underlying asset prices accelerates. Investors tracking current bubble risk indicators will recognise this pattern: it is the structural amplifier that turns a repricing into a rout.
The South Sea Parallel: Institutional Credibility and the Confidence Cliff
The historical resonance here is less about asset prices than about institutional trust. The South Sea Bubble (1720) is remembered primarily as a speculative frenzy, but its underlying architecture was a scheme to restructure British national debt — a transaction that depended entirely on the government's willingness to lend the South Sea Company the credibility of the Crown. When that institutional backing was perceived as wavering, the collapse was not gradual. It was vertical.
Central banks occupy the analogous position in contemporary financial architecture. They are the credibility backstop. When a major emerging-market central bank undergoes a leadership transition during a period of external pressure — and when the world's most important central bank is simultaneously signalling tighter policy — the question markets ask is the same one investors asked in 1720: is the institutional guarantee still intact? The answer does not need to be "no" to cause damage. Uncertainty alone is sufficient to trigger the carry unwind.
For broader equity valuation context, it is worth situating this divergence episode within the current global rate cycle. The 2022–2023 tightening phase was synchronised — almost every major central bank hiked together, which paradoxically limited the currency volatility that divergence typically produces. The current phase is the opposite: the Fed is potentially hiking while the ECB is easing and Asian central banks face conflicting domestic pressures. That asynchrony is the dangerous condition.
The dot-com bubble versus AI infrastructure comparison is instructive here: in 1999–2000, the collapse in US technology valuations transmitted rapidly to emerging markets via reduced risk appetite and dollar strengthening, even though the underlying technology investment was domestically concentrated. The mechanism in 2026 is structurally similar.
What History Suggests Happens Next
Across the full Bubblepedia bubble encyclopedia, episodes of central bank divergence combined with institutional credibility uncertainty share a common path. The initial phase is characterised by elevated volatility but contained damage — markets probe rather than flee. The second phase, triggered by a specific catalyst (a currency break, a policy misstep, a surprise rate decision), produces the disorderly repricing. The interval between the two phases is rarely predictable, but it is almost always shorter than participants expect.
For Indonesia specifically, the historical analogue is the 1997–1998 Asian Financial Crisis, when Bank Indonesia's credibility was tested by a combination of external rate pressure and domestic political uncertainty — and found wanting. That episode is not a forecast. It is a reference point for understanding how quickly confidence cliffs can materialise when the conditions are aligned. Those conditions, in late July 2026, are more closely aligned than at any point in the current cycle.